Artea Bank 2026 Q3 financial review
Net interest income is growing, but where are the profits?
Artea Bank’s Q3 results tell a very different story from its Estonian peers, LHV Group and Coop Pank, both of which reported growing profits.
As with the Estonian banks, Artea’s net interest income showed positive momentum, increasing by 15% YoY and 12% QoQ.
Net interest income
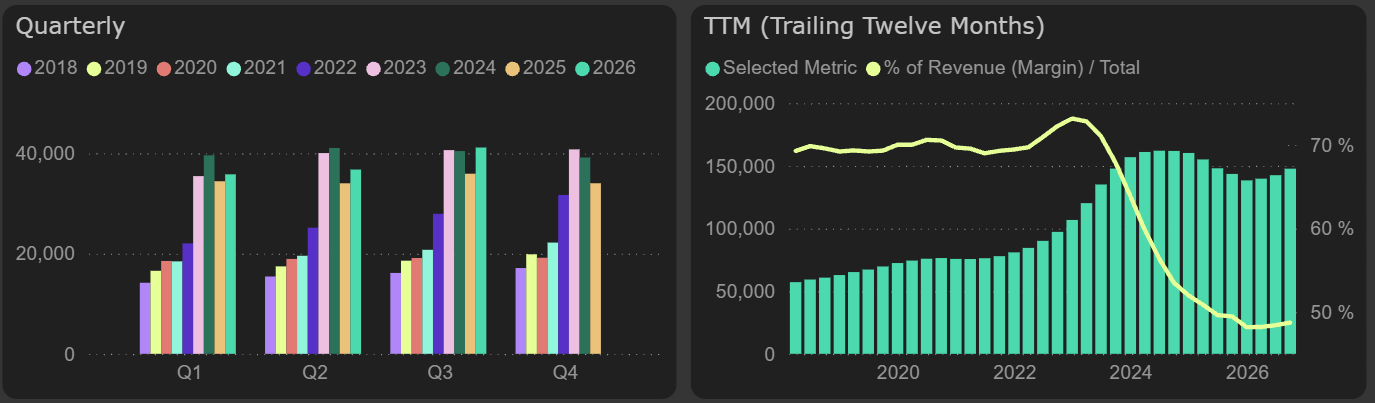
However, both personnel and other operating expenses rose by approximately 24% YoY, with IT and communication costs contributing significantly to the growth in the latter. Result from trading activities (excluding insurance) also swung from a €2.1M gain to a €2.6M loss. As a result, profit before impairment losses declined 29% YoY and 32% QoQ, to €14M.
Profit before impairment losses
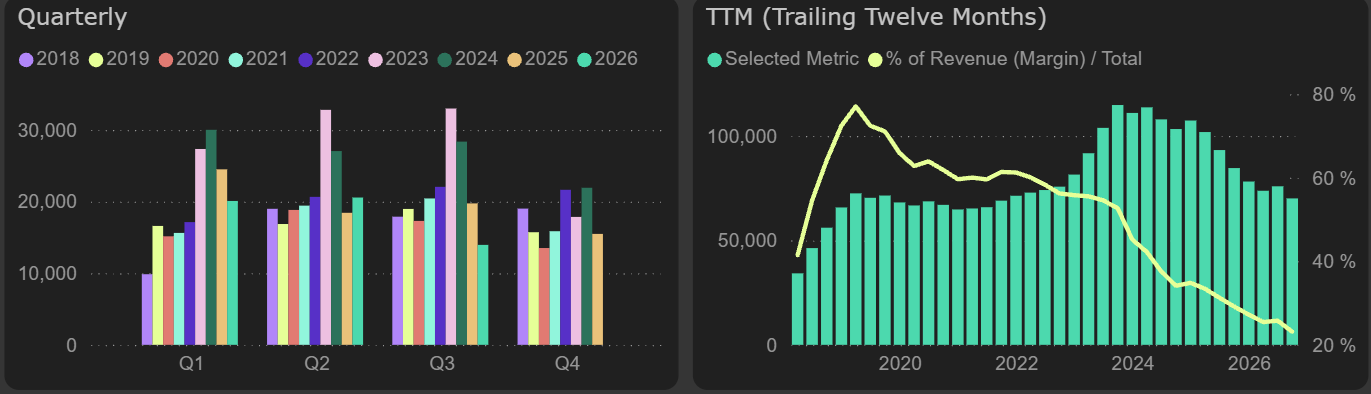
In contrast, LHV Group reported 8% YoY growth in profit before impairment losses, while Coop Pank delivered an even stronger 24% increase. Thus, although net interest income increased at all three banks, only the Estonian banks managed to translate this growth into higher operating profit.
On top of that, Artea recorded €8.1M in impairment losses (primarily related to loan loss provisions), bringing quarterly net profit down to just €4.7M, compared to €16.5M a year earlier. This marks the third consecutive year of declining Q3 profits, down from €24.2M in Q3 2023.
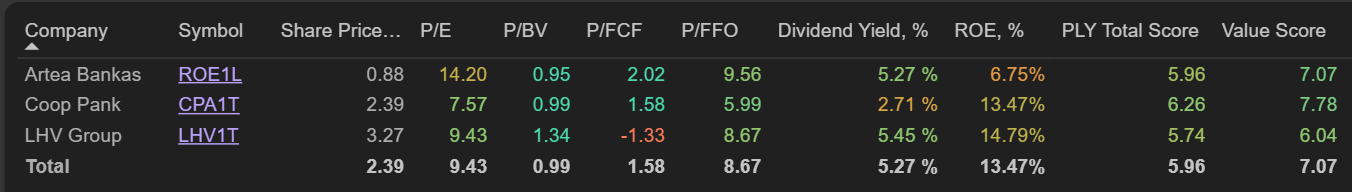
Artea’s market valuation metrics also appear relatively unattractive. Its P/BV stands at 0.95x, below LHV (1.34x) and almost in line with Coop Pank (0.99x). However, the picture is reversed when looking at P/E multiples: Artea trades at 14.2x earnings, compared to 9.4x for LHV and 7.6x for Coop Pank. Meanwhile, Artea’s ROE stands at just 7% – roughly half that of LHV (15%) and Coop Pank (13%).
Valuation metrics


Apranga Group | 2026 Q3 | Could 2026 be a record year?
Apranga delivered a strong Q3, with revenue up 8.8% YoY to 89.5M and net profit jumping 34% to 8.2M. Even more impressively, TTM net ...

